Why Flood Insurance Is a Smart Question to Ask
If you’re reading this, you’re probably wondering whether flood insurance is actually worth the investment. You’re not alone. It’s one of the most common questions homeowners and property owners ask, especially when reviewing or renewing their insurance policies.
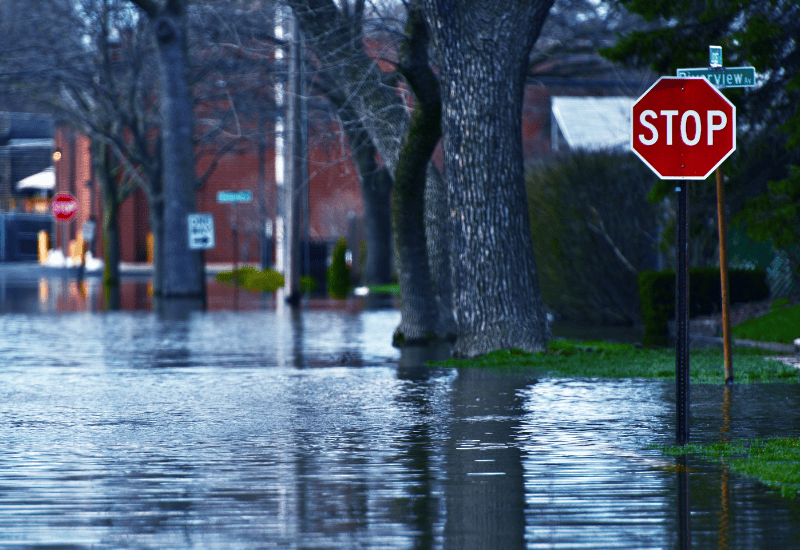
Here’s the truth: Flooding is the most common and costly natural disaster in the U.S., and most homeowners insurance policies do not cover flood damage. That means even a minor flood could leave you paying out-of-pocket to repair your home, replace appliances, and rebuild what was lost.
The good news? You’ve got options. And you don’t have to figure it out alone. At C.T. Lowndes & Company, we help South Carolinians like you buy flood insurance for your property.
We’re breaking down how flood insurance works, what it covers, and whether it’s the right move for you.
What Is Flood Insurance and What Does It Cover?
Flood insurance protects your home and belongings from damage caused by rising water that comes from outside, like heavy rain, rising rivers, or storm surge. It’s designed to cover flood damage from events that aren’t included in homeowners policies.
There are two main parts to a standard flood insurance policy:
-
Building coverage: Protects the physical structure of your home, including foundation walls, plumbing systems, electrical systems, built in appliances, and more.
-
Contents coverage: Covers your personal belongings like furniture, electronics, window blinds, and valuable items.
Flood insurance does not cover everything. Things like swimming pools, temporary housing, or damage from sewer backups (unless directly caused by flooding) are typically excluded. That’s why it’s essential to review your flood insurance coverage with a knowledgeable insurance agent.
Doesn’t My Homeowners Insurance Cover Flood Damage?
This is a big misconception. Most homeowners insurance policies do not cover flooding. Even if your home is damaged by a hurricane, if the damage is caused by water rising from outside, it’s considered flooding and won’t be covered unless you have a flood policy.
That’s why you need a separate policy specifically for floods. Otherwise, you could be left responsible for thousands, or even hundreds of thousands, in repairs.
What Is the National Flood Insurance Program (NFIP)?
The National Flood Insurance Program (NFIP) is a federally backed program created under the National Flood Insurance Act and managed by the Federal Emergency Management Agency (FEMA). It offers standardized flood insurance policies through participating insurance providers.
NFIP policies are available in communities that agree to enforce floodplain management regulations. These communities must also adopt FEMA’s flood map standards. Sounds like a no brainer for a community but there are zones where a flood zone has not been designated in an attempt to preserve coastal barriers by discouraging development. This is called the Coastal Barrier Resources Act (CBRA).
Important facts:
-
There’s a 30 day waiting period for most NFIP policies to take effect so plan ahead.
-
NFIP sets specific coverage limits, which may not be enough for higher-value homes.
-
NFIP policies are available through licensed insurance agents, including our team at C.T. Lowndes.
Who Needs Flood Insurance (Even If You’re Not in a High-Risk Flood Zone)?
You might think, “I’m not in a high risk flood area, so I don’t need it.” But consider this: Over 25% of all flood insurance claims come from homes located outside high risk areas.
That’s because flood risk isn’t limited to FEMA’s flood map. New development, community flood map changes, aging infrastructure, and even melting snow can affect your flood exposure.
Here’s why property owners should consider it:
-
Flooding can happen anywhere it rains.
-
Just one inch of water can cause up to $25,000 in damage.
-
Mortgage lenders may not require flood insurance in low-risk areas, but that doesn’t mean the risk is zero.
Cost of Flood Insurance: What You Can Expect
The cost of flood insurance depends on several factors:
-
Location and flood risk level
-
Home elevation and construction type
-
Foundation walls, plumbing systems, and electrical and plumbing systems
-
Type of policy: NFIP policy vs private flood insurance
-
Amount of building coverage and contents coverage
In low-risk zones, a preferred risk policy through NFIP can start as low as a few hundred dollars per year. Higher-risk areas will cost more, but the protection often outweighs the financial risk of going without.
While having your home, auto, and flood insurance with the same agency doesn’t mean discounts on your flood insurance policy it does make things more convenient having all policies under one roof, even though it is always written as a separate policy.
NFIP vs Private Flood Insurance: What’s the Difference?
While the NFIP provides reliable coverage, it’s not your only option. Private flood insurance is offered by private insurers and may offer:
-
Higher coverage limits
-
Shorter or no 30 day waiting period
-
Optional living expenses coverage
-
Broader protection for valuable items or additional structures like detached garages
Private flood policies may be ideal for homes in high risk flood zones or for property owners who need more flexibility. At C.T. Lowndes, our insurance agents can help compare NFIP and private flood options.
How to Buy Flood Insurance the Right Way
Here’s what to do if you’re considering flood insurance:
-
Talk to a local insurance agent, ideally someone who understands flood insurance program NFIP rules and private flood alternatives.
-
Review your flood risk. FEMA’s flood maps are a good starting point, but local insight matters too.
-
Assess your coverage needs. Think beyond the structure. Consider solar energy equipment, window air conditioners, water heaters, contents coverage, and more.
-
Buy flood insurance early. Remember the 30 day waiting period on NFIP policies.
Real Talk: Is Flood Insurance Worth It?
So let’s get back to the big question: Is flood insurance worth it?
If your home, savings, or business would take a hit from a flood, it probably is. Think of it like this:
-
A policy costing $400–$700 a year could protect against tens or hundreds of thousands in flood damage.
-
Even outside high risk areas, flooding happens. And when it does, it’s fast and expensive.
-
You don’t have to be in a storm path to suffer. Heavy rains and poor drainage can do just as much damage.
At the end of the day, flood insurance coverage is about protecting your investment and keeping you from having to start over financially.
What to Do After a Flood: Making a Flood Insurance Claim
If your property floods and you have coverage, here’s what happens next:
-
Document everything. Take photos of personal belongings, foundation walls, built in appliances, and damaged items.
-
File your flood insurance claim through your insurance provider as soon as it’s safe.
-
Work with adjusters to assess damage and calculate your settlement.
-
Some flood insurance policies also cover living expenses while repairs are made, depending on your provider.
Once floodwaters recede, the recovery process can still take months. But having the right coverage helps you recover faster, both financially and emotionally.
Helpful FEMA links for Recovering from a Flood
Make an Informed Decision Today
Don’t Wait for the Water to Rise
You don’t have to live in a high risk flood zone to feel the effects of flooding. Whether it’s from a storm, backed-up drain, or rapid rainfall, water can turn your world upside down in minutes.
At C.T. Lowndes & Company, we’ll help you understand your flood risk, review your options, and purchase flood insurance that fits your needs. Our experienced insurance agents know the local landscape and how to recommend the right insurance companies, whether that’s private flood or NFIP coverage.
Call us today or request a quote online. Let’s protect what matters most before the next storm hits.
Flood Insurance FAQ
Is flood insurance worth it if I’m not in a flood zone?
Yes. About 25% of all flood insurance claims come from low- to moderate-risk zones.
Does flood insurance cover all types of water damage?
No. It specifically covers flooding from outside sources, not leaks or burst pipes inside the home.
How do I know if I need flood insurance?
Check FEMA’s flood map and talk to an insurance agent to assess your risk.
Is NFIP insurance better than private flood insurance?
It depends. NFIP is widely available but has coverage limits. Private flood insurance offers flexibility and higher limits but can change their guidelines on an annual basis.
How long does it take to get flood insurance?
NFIP policies have a 30 day waiting period. Some private insurers offer quicker activation but usually not when a storm warning has been issued.